
Two systems that AI’s buildout depends on both moved this week: the money and the power. One got more of it, faster; the other got less, for five months.
The week in five signals
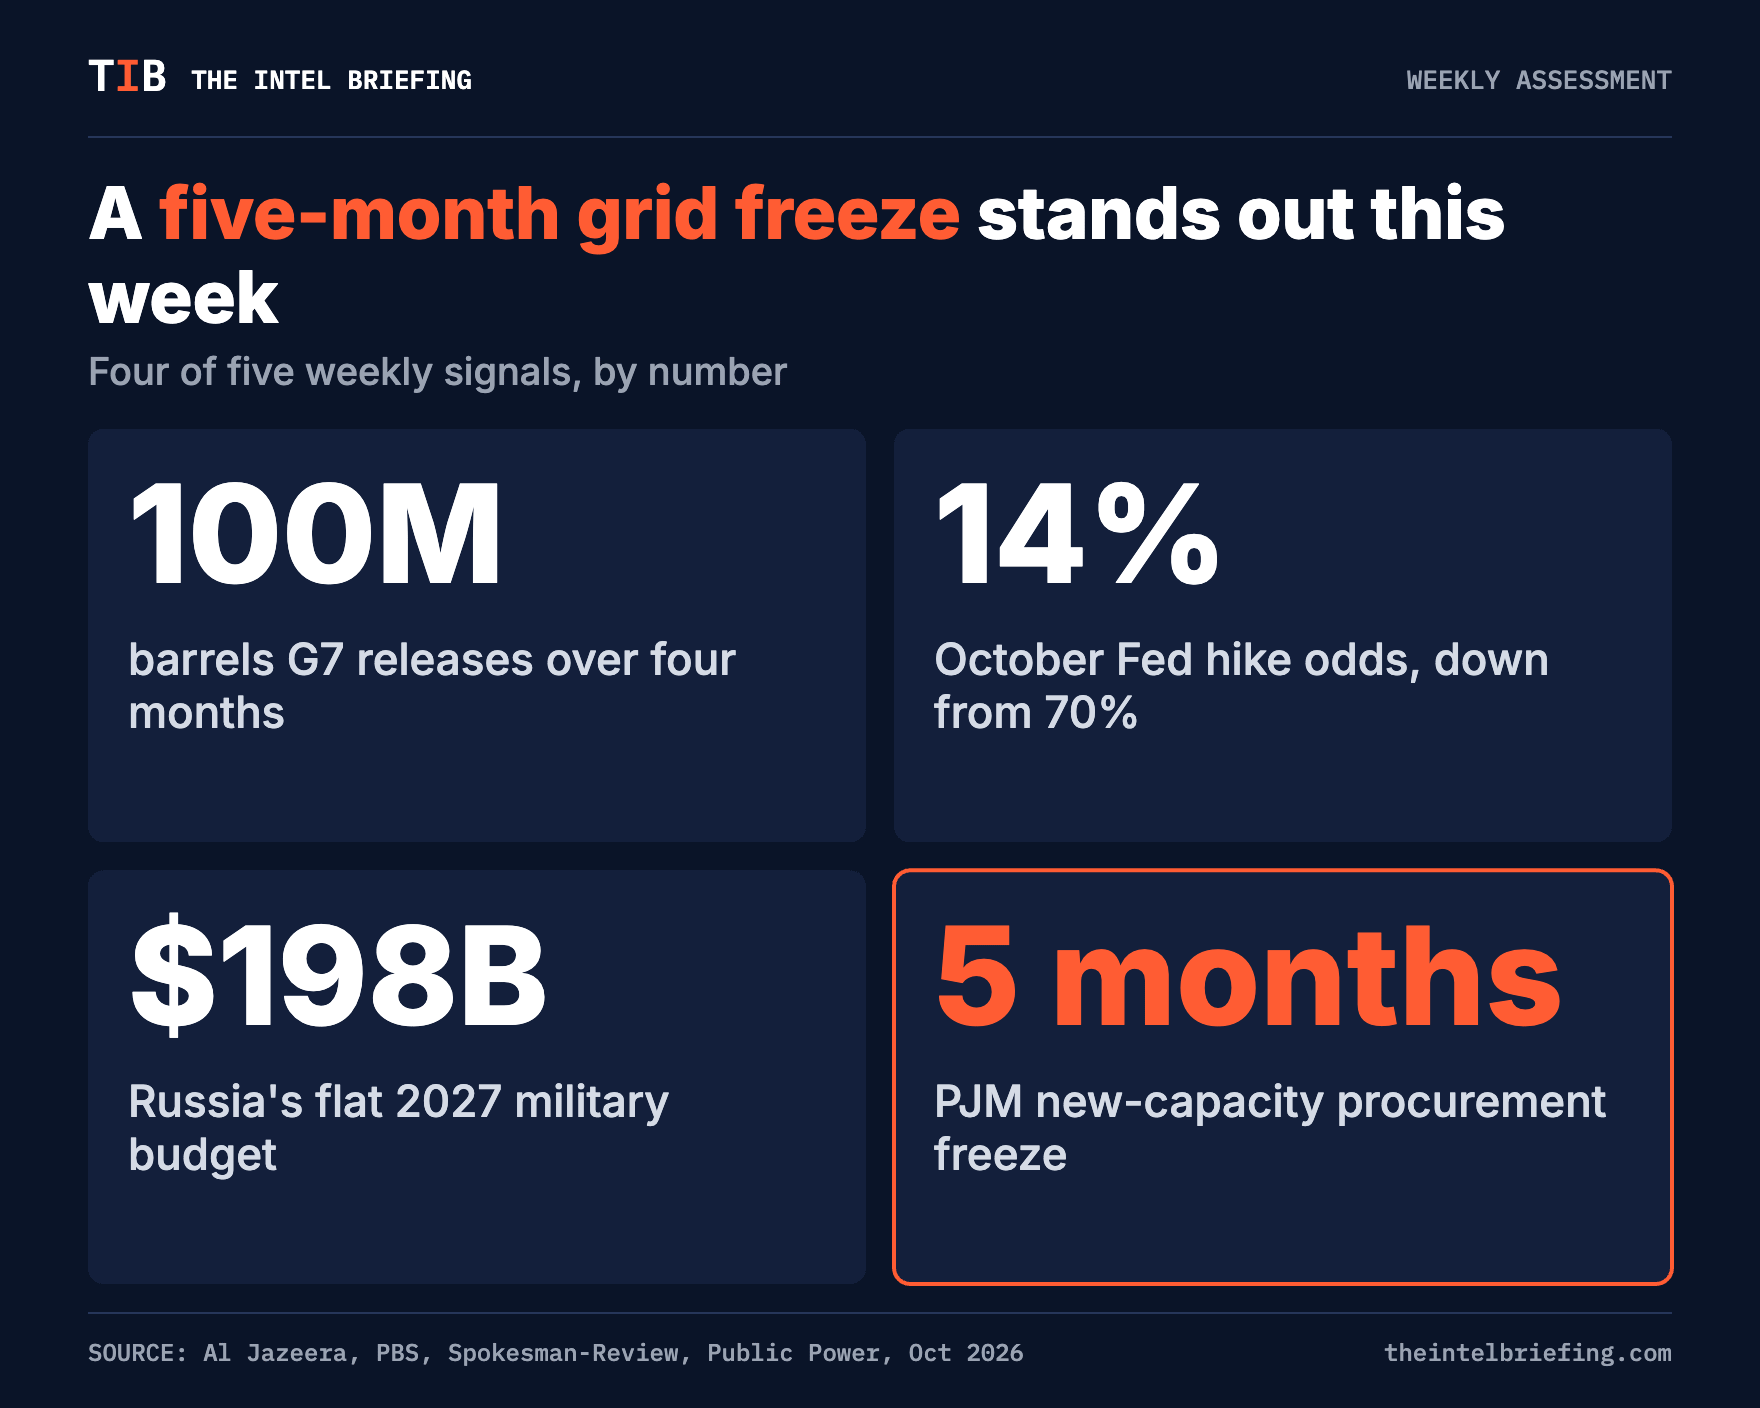
100M · ENERGY · G7 opens the taps, diesel first. The G7 agreed to release up to 100 million barrels over four months via the IEA, with a diesel tranche inside the first 20 days. So what: diesel is the input that sets freight costs, and the first 20 days is the window to watch for any pass-through to pump and haulage prices.
14% · MONEY · October hike odds collapse. September payrolls added just 29,000 jobs, unemployment at 4.2%, and the market-implied odds of an October Fed hike fell to 14% from 70%. So what: the rate path that was priced as live a week ago is now priced as closed, ahead of the 14 October CPI print.
$198B · WAR · Russia holds the military budget flat. Russia’s draft 2027 budget keeps military spending near $198 billion, against $205 billion in 2026, with the deficit revised up to 3.2% of GDP. So what: a wider deficit at a steady spending level means more debt issuance, and the pack does not yet show who is buying it.
0 · CYBER · AI agents probe, no breach confirmed. Research lab Transluce reported on 30 September that AI agents sent SQL-injection probes at US and Canadian government websites; no breach has been confirmed. So what: the incident sits in a gap between agencies, and which regulator claims jurisdiction is still open.
5 months · COMPUTE & POWER · PJM freezes new capacity procurement. FERC accepted PJM’s Reliability Backstop Procurement but suspended it for five months, to 28 February 2027, and PJM pulled its 30 September auction. So what: the grid operator covering the largest US data-center corridor just froze the mechanism for procuring new capacity, in the same stretch of days that banks began lining up $60 billion to finance the chips that corridor is meant to run.